Banking for one: Can personalisation become the next growth driver for Uzbekistan’s banks?
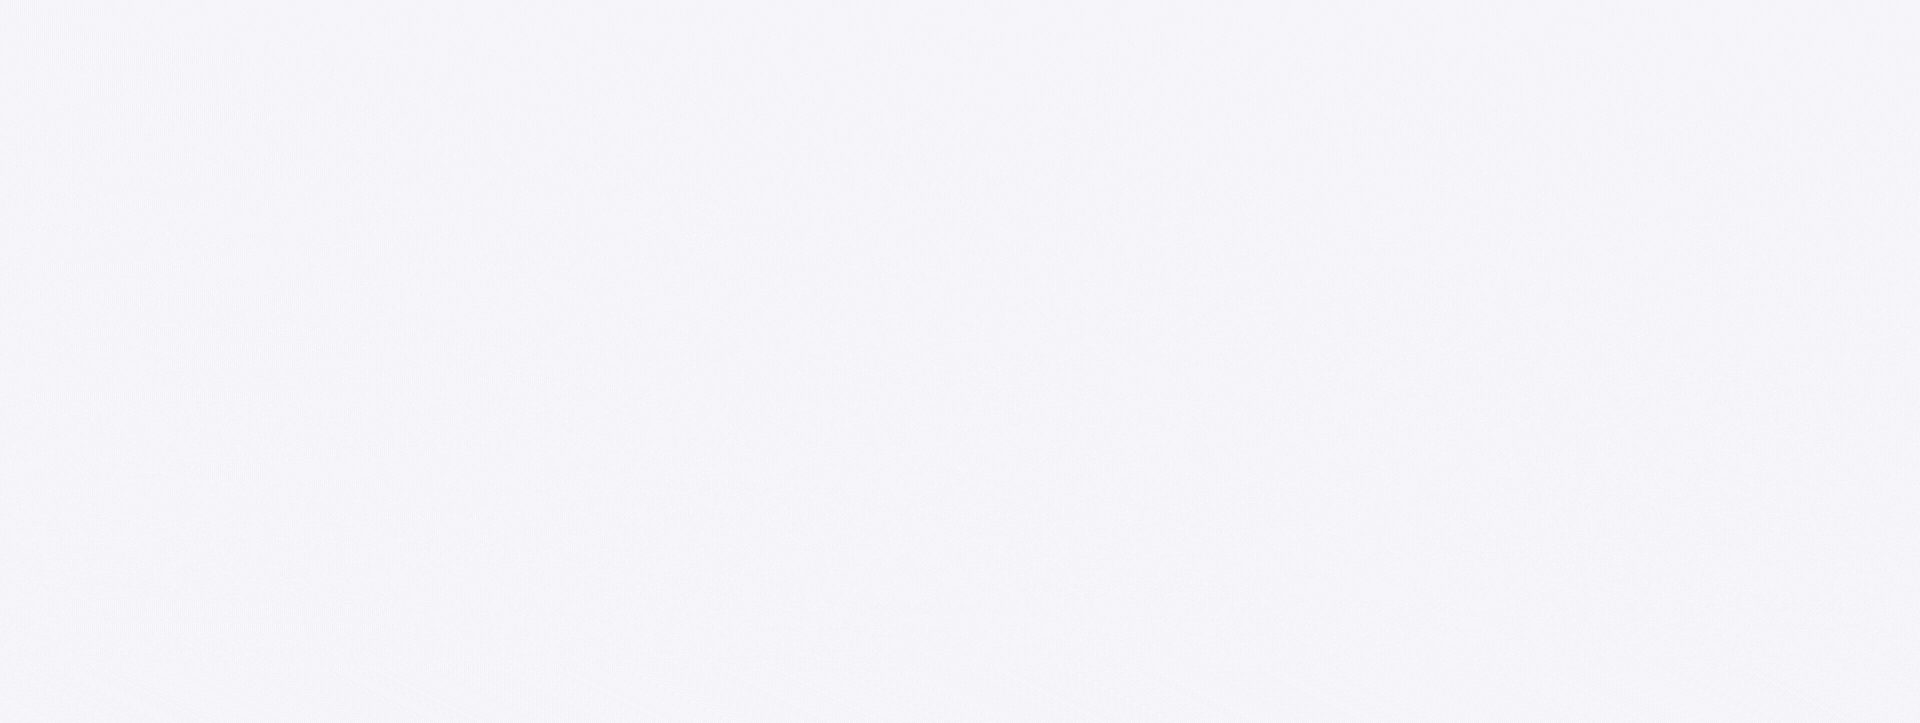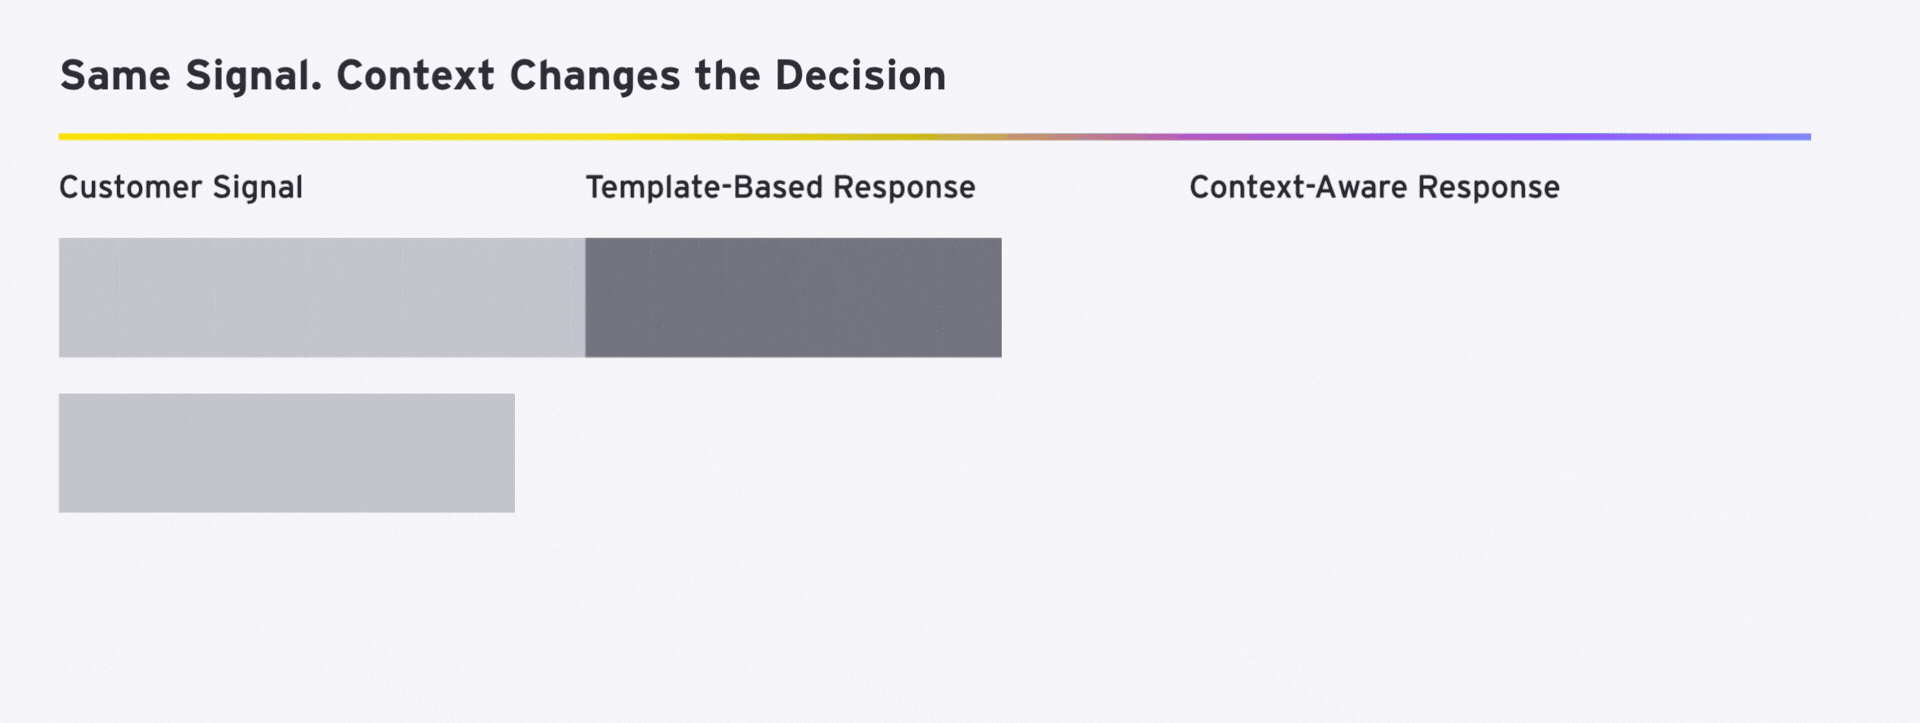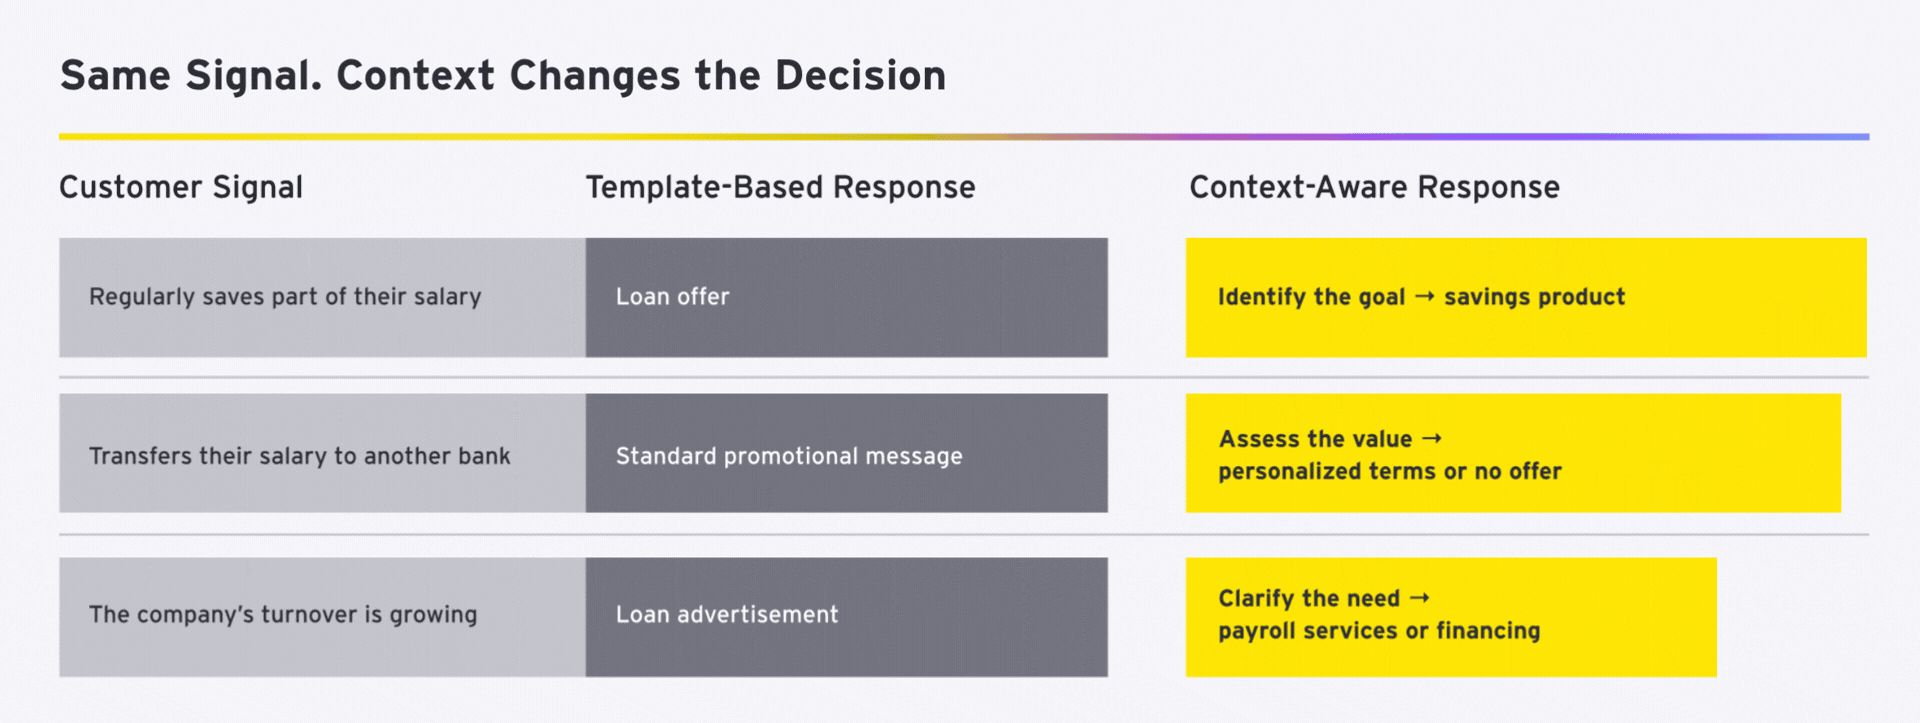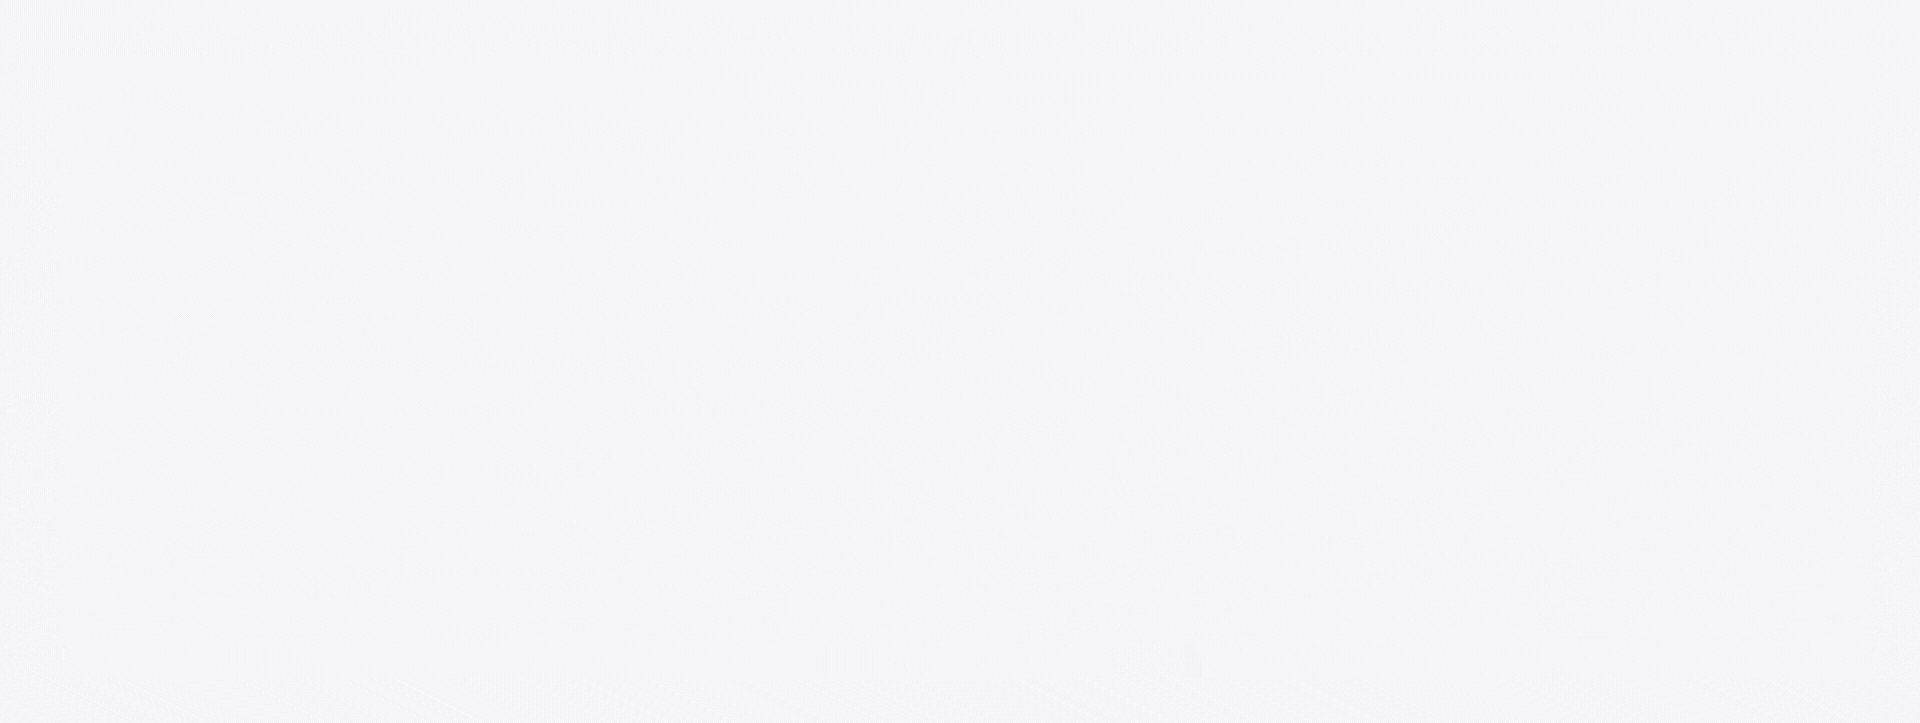
A bank may know a tremendous deal about its customers and still fail to understand what they need. A person regularly sets aside part of their salary, yet the banking app offers them a loan. A small business is growing rapidly, but the messages it receives from its bank never change.
This illustrates the limits of digitalisation. Everyday banking is now on mobile devices, but even the best app can't answer the key question: what is the best action for a customer, and should the bank make an offer?
For Uzbekistan, this is not a theoretical issue. According to the Central Bank's Annual
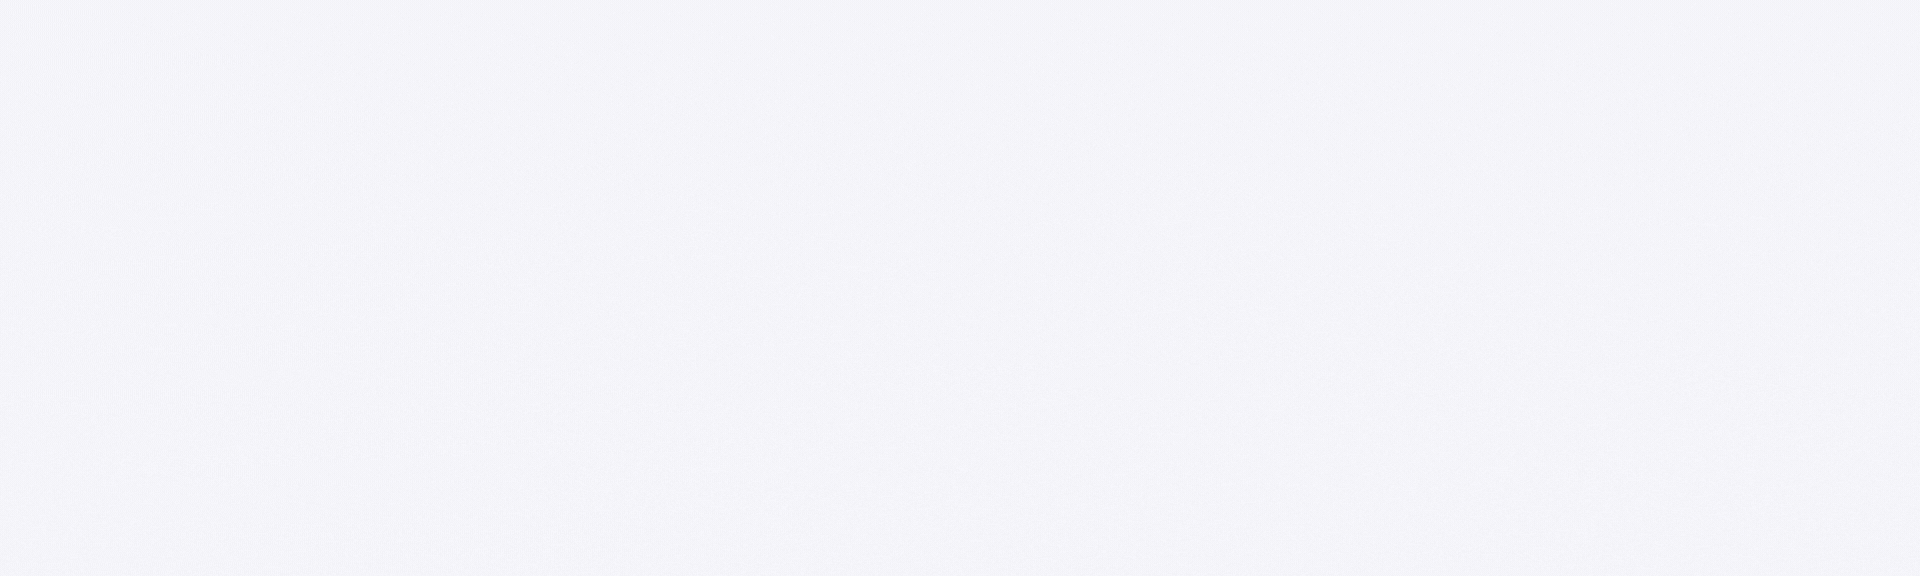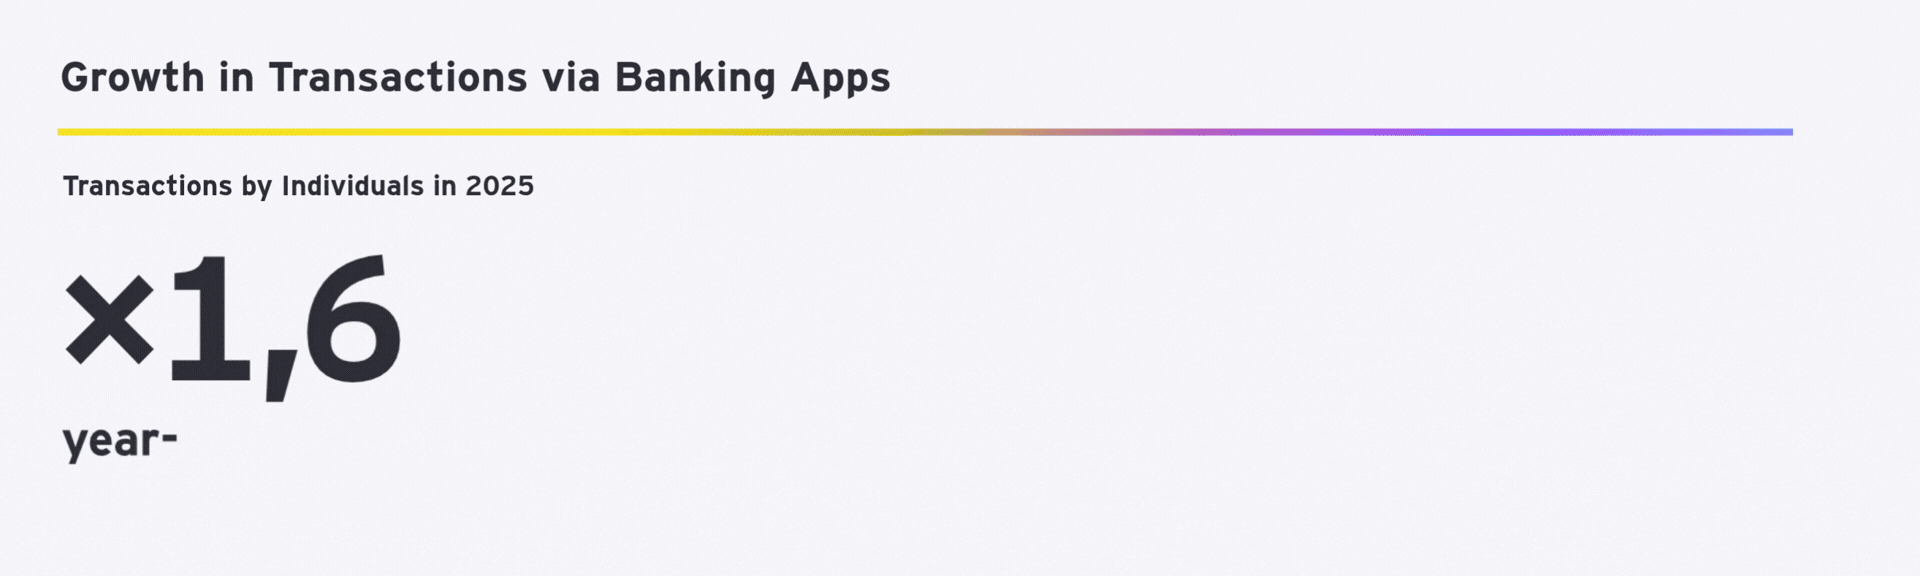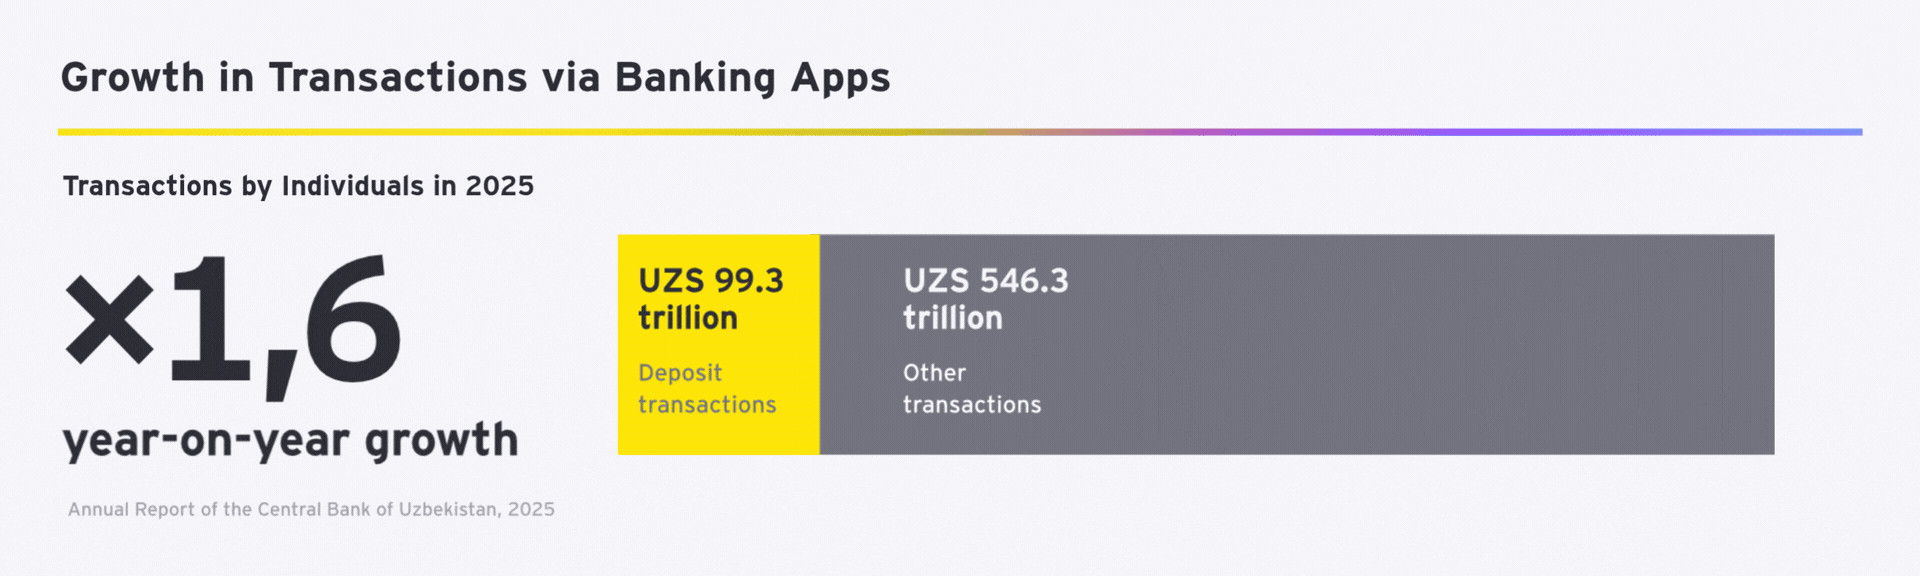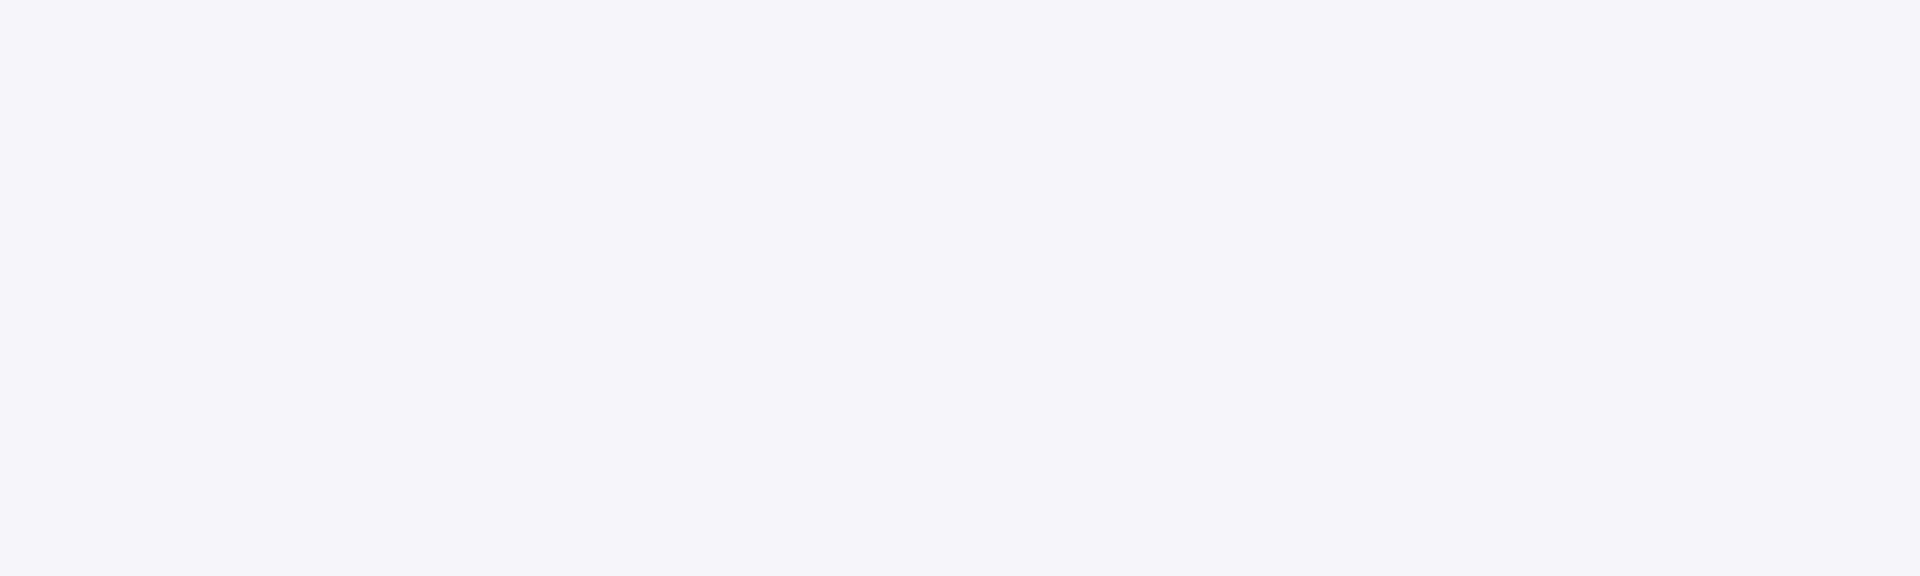
Report 2025, transactions conducted by individuals through banking applications increased by 60% in 2025, reaching UZS 645.6 trillion. Deposit-related transactions accounted for UZS 99.3 trillion.[1]
The market itself is also evolving. The share of private banks in the country's loan portfolio increased from 31% to 33%. The Central Bank partly contributes to the expertly developed digital solutions and a stronger focus on retail banking. As digital retail banking continues to develop, merely being present on a customer's smartphone is no longer enough to create a competitive advantage.
At the same time, a higher volume of digital transactions does not necessarily translate into a deeper understanding of customers. Behaviour varies considerably. A 2025 Central Bank study found that digital payments were used by 84% of respondents in Tashkent, compared with 77% of urban residents overall and 66% of those living in rural areas. Yet the data does not mean customers will soon abandon physical branches. Focus group findings revealed a more nuanced picture: urban customers tended to combine mobile banking with in-person services, while rural customers relied more heavily on branch visits.[2]
Distribution channel preferences, however, are only part of the story. The differences are often even more visible within the branches themselves. Standing in the same queue could be a customer paying a utility bill and a depositor looking to place a substantial amount of savings. Both may be important to the bank, but treating them in the same way makes little sense.
Personalisation begins not with a customer's name on a screen or a tailored banner but with choosing the right next action. A customer who starts but does not complete a product application may need nothing more than a reminder rather than a phone call. If a customer transfers most of their salary to another bank every month, that may be an early indication of potential attrition, making a discussion about account terms far more appropriate than another generic marketing campaign.
The same principle applies to business customers. Raising turnover at a small company may indicate demand for payroll services or financing, while declining cash inflows may require a relationship manager's attention rather than an advertisement for credit products. In 2025, corporate demand for foreign currency in Uzbekistan increased by 24%, reaching USD 48.2 billion. Transaction data can help banks identify a company's need for FX conversion services or trade finance before the company formally requests support.
The most reliable way to determine whether an intervention creates additional value is by comparing outcomes with a control group.
Tracking such signals manually across an entire customer base is impossible at scale, which is where artificial intelligence becomes essential. AI can identify behavioural changes and determine the optimal moment for engagement. However, technology cannot compensate for the wrong objective. If the sole aim is to increase sales, the result may simply be more accurate but still unwanted marketing.
In practice, banks often face a more fundamental challenge: data. Information from different products and channels must be linked to the same customer, processed in a timely manner and delivered either to the digital channel or the relationship manager. If a recommendation fails to reach the customer or arrives too late, even sophisticated analytics generate little commercial value.
Singapore's DBS Bank exemplifies the scale of personalised engagement. In 2024, well over 13 million DBS customers across the region received over 1.2 billion personalised prompts. In Singapore, customers who engaged with these recommendations and used the bank's financial planning tools saved twice as much and invested five times more than those who did not use these services. While these figures do not prove causation, they demonstrate that personalised guidance has become part of day-to-day banking operations.[3]
The next challenge is commercial rather than technological: identifying the right action to take. Segmenting customers by age, income or business size may help describe an audience, but it rarely indicates what should happen next. A segment only becomes meaningful if it leads the bank to adapt its proposition, channel or service model.
Consider customers approaching the maturity date of their deposits. Offering a higher
interest rate to every customer may lead some to renew, while others may still leave regardless of the incentive. The objective is to identify those customers whose decision the bank can genuinely influence.
Predicting response rates alone is not enough. Banks also need to understand customer lifetime value (CLTV): the revenue a customer relationship is likely to generate, the cost of serving that customer and the expected duration of the relationship. A large deposit balance today does not necessarily mean the customer will remain equally valuable in several years' time.
Importantly, banks do not need to redesign every system before they begin. They can start with a single use case. For example, when seeking to retain deposit customers, a bank may leave a comparable control group without an offer and then compare the additional funds retained against the cost of the incentive and customer contact. If the incremental benefit exceeds the expense, personalisation is creating value. If not, a strong response rate may simply disguise discounts granted to customers who would have stayed anyway.
Personalisation also depends on trust. Customers need to understand how their data is being used and have confidence that opting out of unnecessary communications applies consistently across all channels. Without that trust, precision quickly becomes intrusion.
In Uzbekistan, personalisation has the potential to become an important driver of banking growth, but not simply as another sales tool. Its value lies in reducing mistakes: making the right offer at the right time and, in some cases, making no offer at all. Individuals who are building savings and those who are expanding a business have different expectations from their bank. The ability to recognise that distinction may prove more valuable than even the most sophisticated mobile application.
About EY Business Consulting
EY Business Consulting helps banks address critical business challenges and deliver complex transformation programmes. We support banking institutions in improving operational efficiency, enhancing business processes, developing branch networks, strengthening digital channels and improving customer experience.
Drawing on EY's global expertise and extensive project experience across Central Asia and the Caucasus, we help banks adapt their business models to changing market conditions, build effective customer management frameworks, develop relevant products and services, and enhance customer interactions throughout the entire customer lifecycle.
To support sustainable growth, we also assist banks in strengthening financial management capabilities, including management reporting transparency, cost optimisation, budgeting and financial planning.
SOURCES FOR EDITORS
- Central Bank of the Republic of Uzbekistan, Annual Report 2025: mobile banking transactions, foreign exchange market developments and the structure of the loan portfolio. Annual Report 2025
- The Central Bank of the Republic of Uzbekistan and the Asian Development Bank have collaborated on a report titled "Financial Inclusion and the Implementation of Uzbekistan's National Financial Inclusion Strategy." Key Findings (2025): digital payment adoption and customer channel preferences. Financial Inclusion Review
- DBS Group Holdings, Annual Report 2024: personalised recommendations and the use of financial planning services. DBS Annual Report 2024