Uzbekistan’s taxation policy: Reform outcomes and the road ahead
Over the past several years, Uzbekistan’s tax system has evolved against the backdrop of rapid economic growth, large-scale reforms, and steadily increasing economic transparency. This provides a timely opportunity to assess the effectiveness of the country’s tax policy, not merely through individual legislative changes but through their tangible outcomes.
Such an assessment requires looking at several dimensions simultaneously: tax revenue performance, developments in tax legislation, approaches to tax incentives, and the effectiveness of tax administration.
Tax revenues: What is driving growth?
Any discussion of tax policy typically starts with government revenue. However, absolute figures alone tell only part of the story. More important are the trends behind those figures and their relationship to broader economic indicators.
For example, personal income tax (PIT) revenues increased by 20% in 2025, a strong result by any measure. Yet corporate income tax (CIT) revenues rose by 37%, while value-added tax (VAT) increased by only 14%. This raises an important question: what is driving tax revenue growth? Is it economic expansion, legislative reforms, improvements in tax administration, or a reduction in informal economic activity?
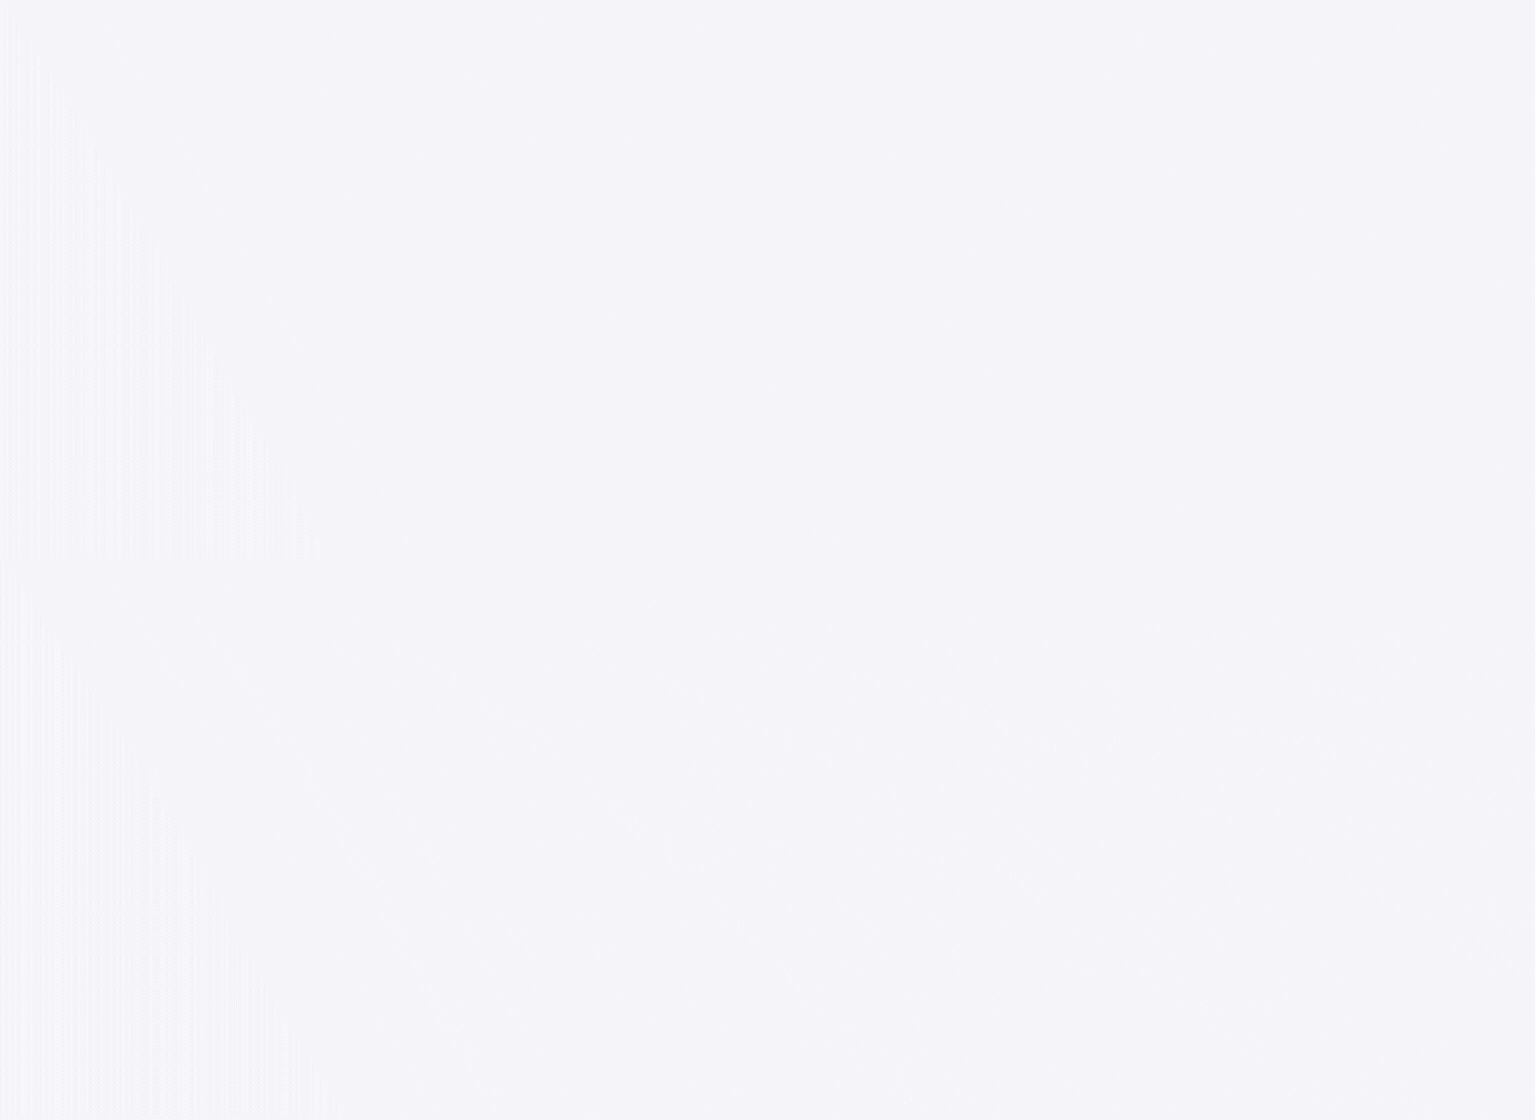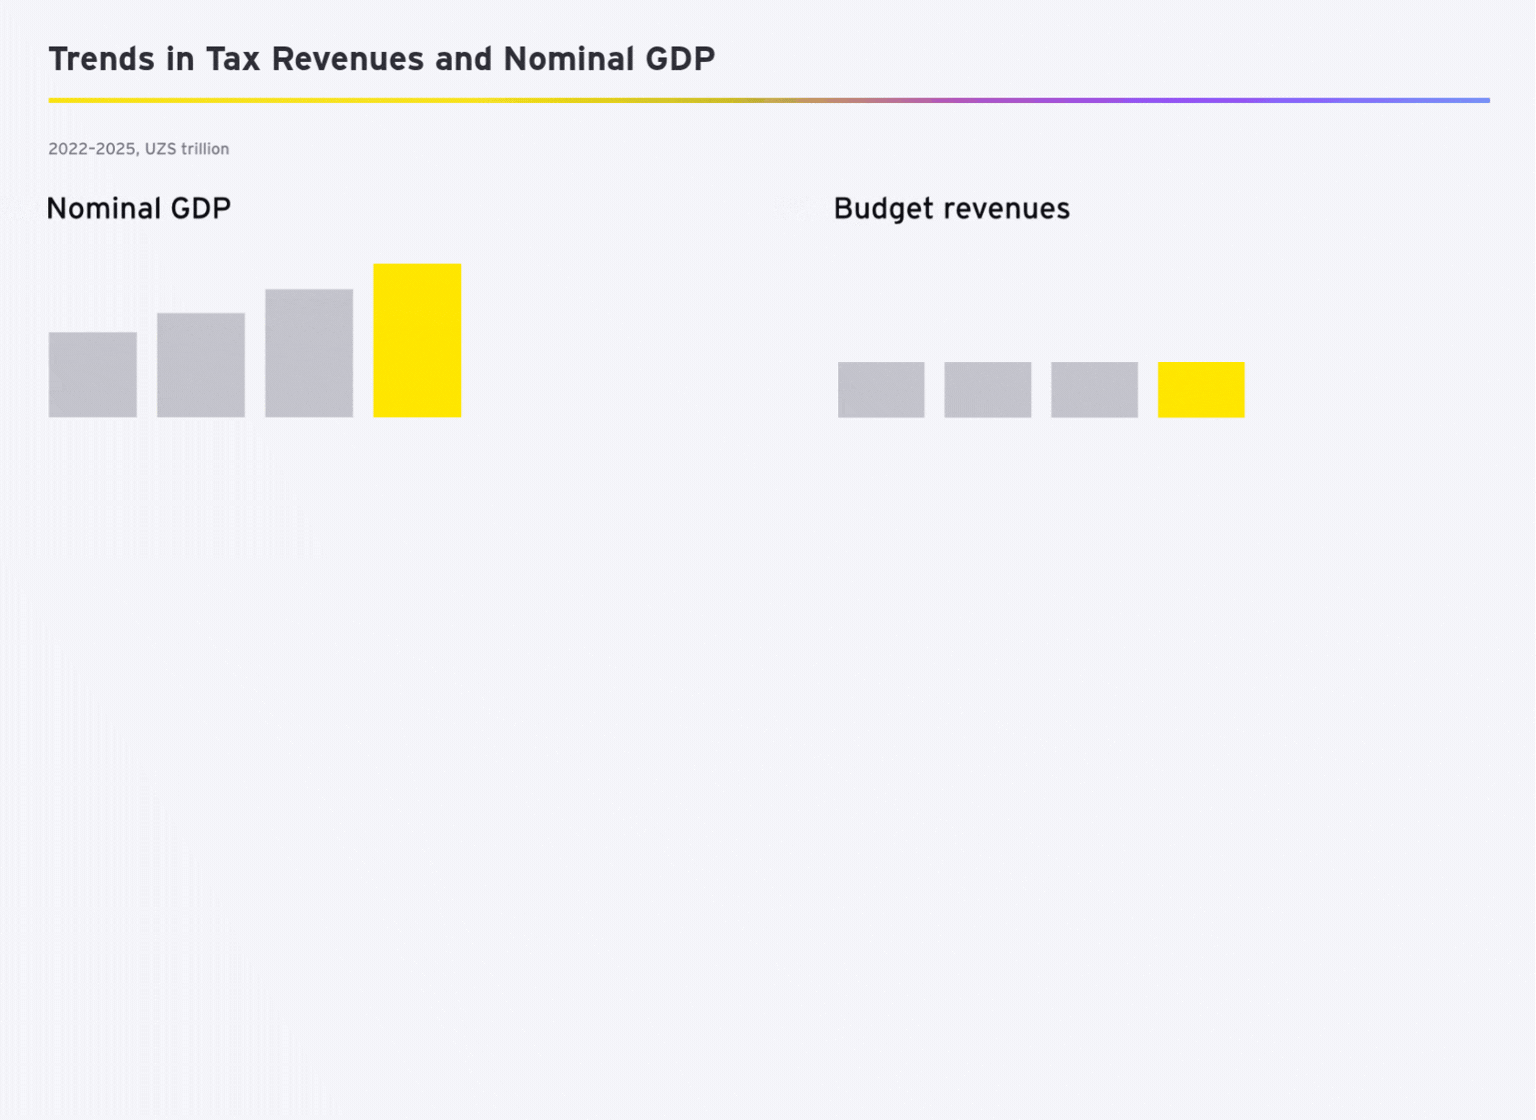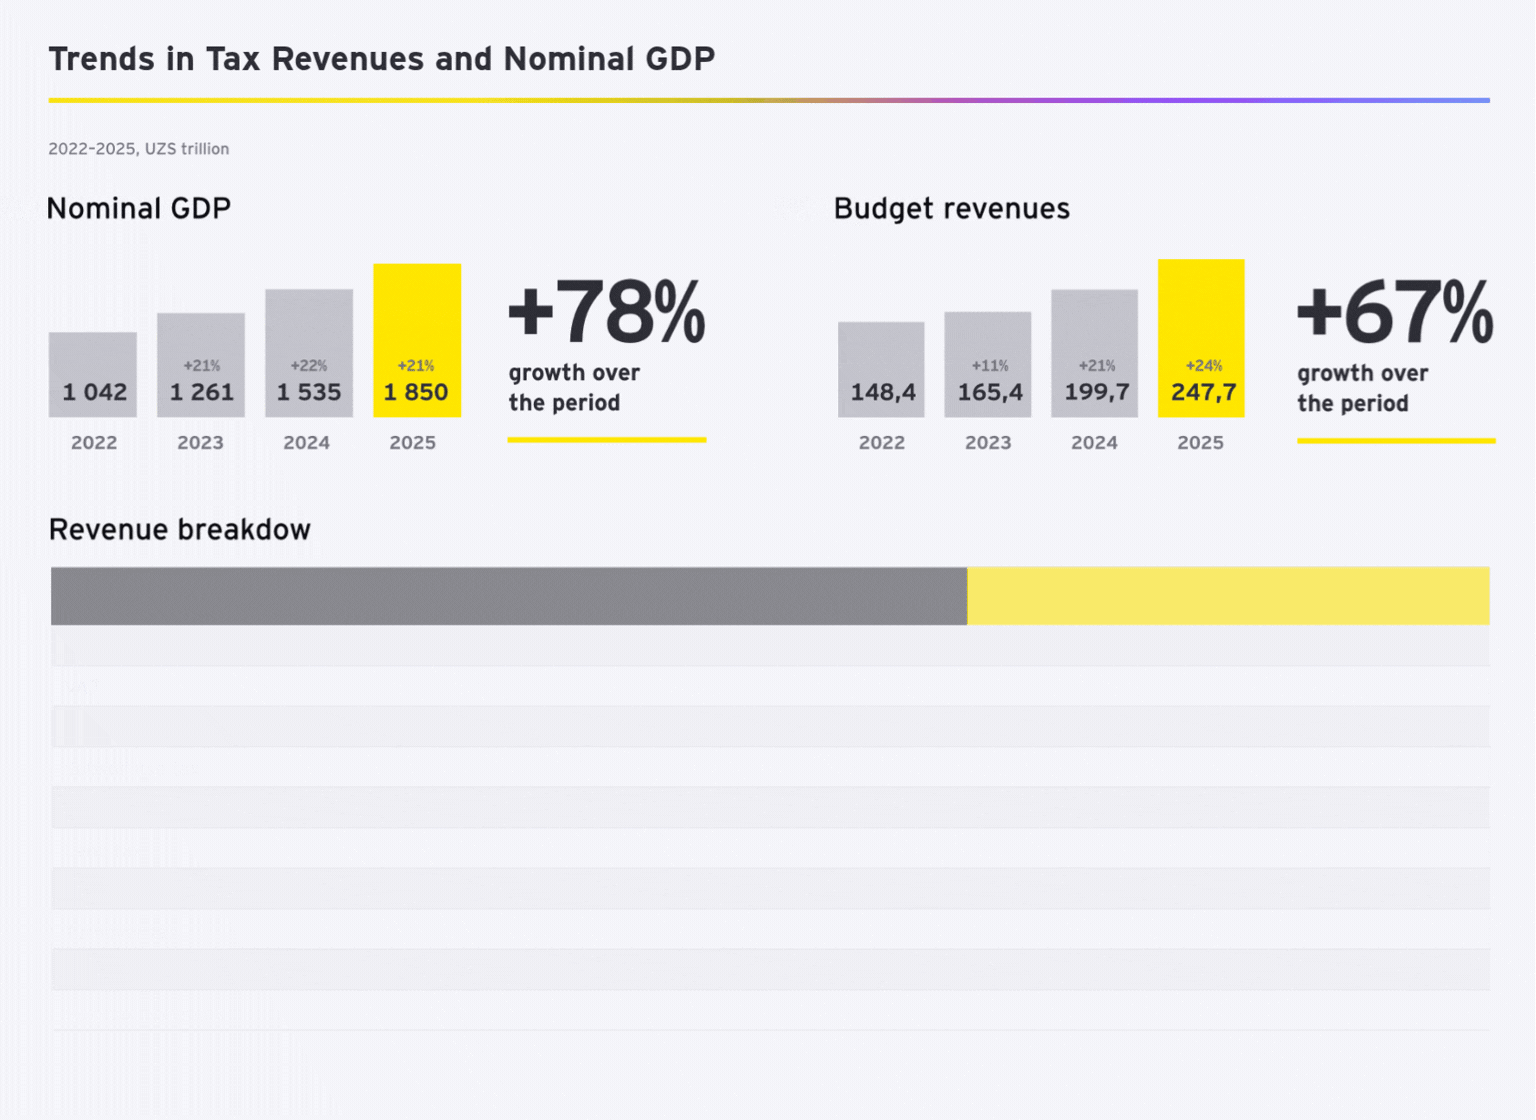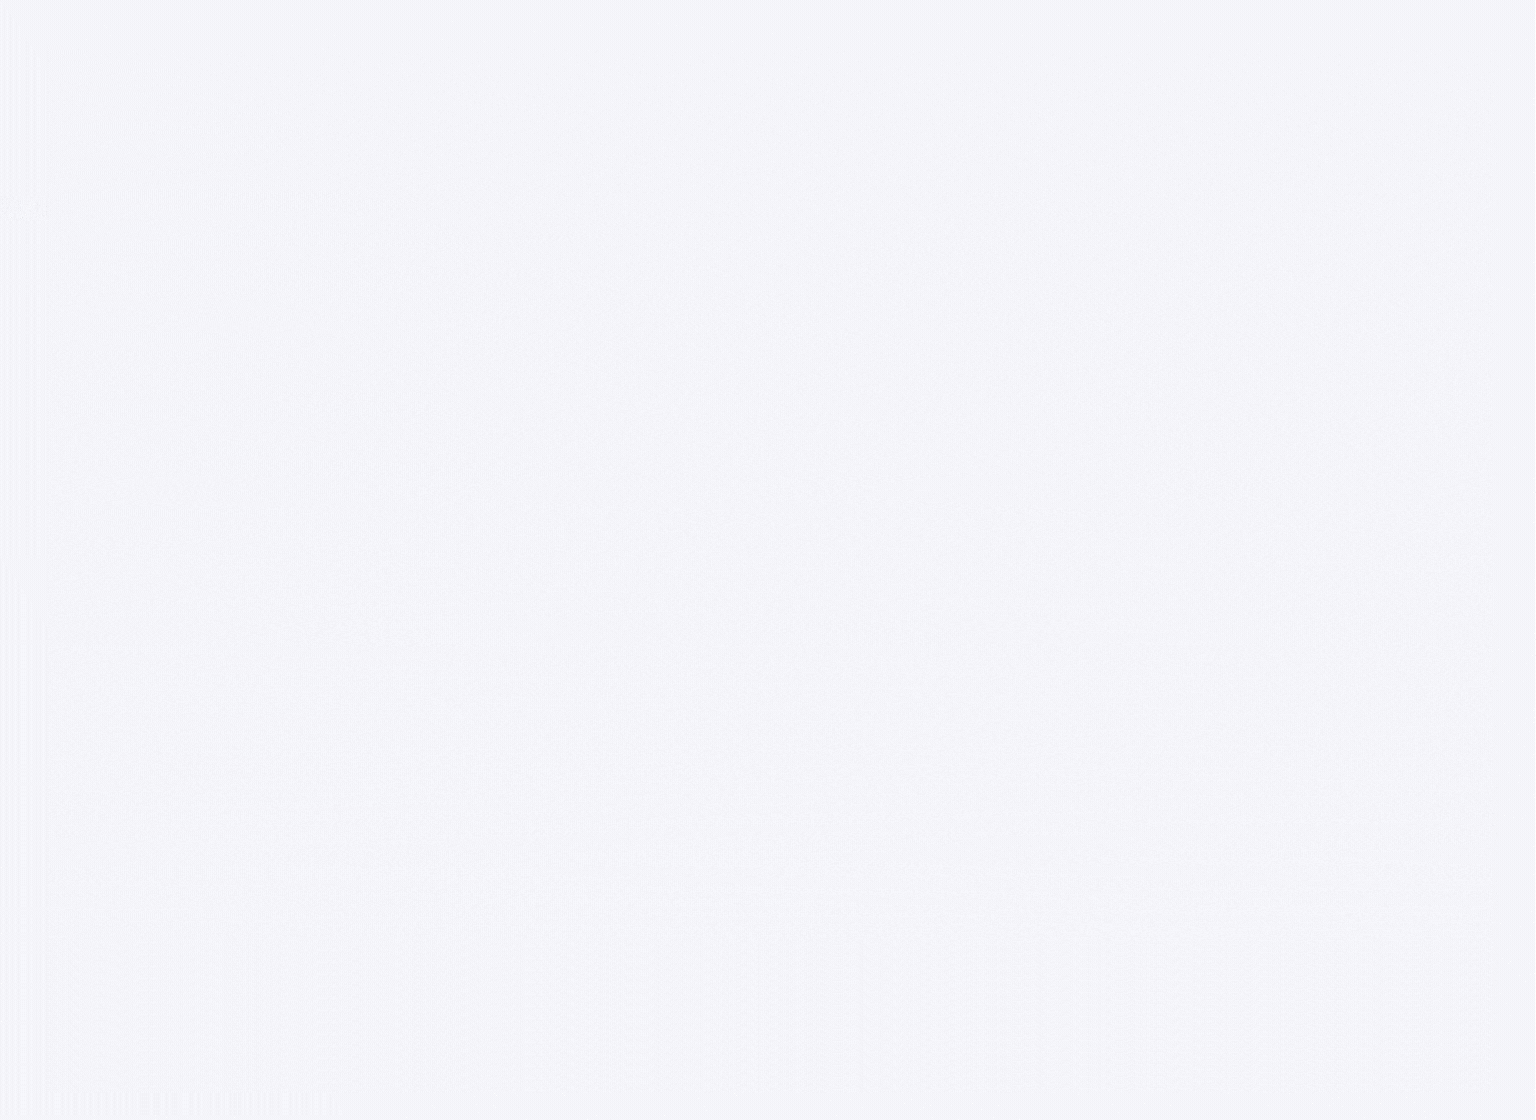
Some of these questions can be addressed by comparing tax revenue growth with changes in nominal GDP. Nominal GDP serves as a more meaningful benchmark than real GDP because taxes are typically levied on the current value of goods and services produced.
The publication of GDP estimates adjusted for the non-observed economy in 2025 and 2026 adds another valuable dimension to the analysis. It allows for a more accurate assessment of how tax revenue trends correlate with changes in the size of the informal sector.
- Corporate income tax. Over the past three years, corporate income tax revenues have nearly doubled, substantially outpacing nominal GDP growth, even after accounting for the non-observed economy, which largely falls outside the corporate profit tax base. This strong performance reflects a combination of factors, including favourable market conditions, particularly higher export metal prices, legislative changes such as the abolition of the zero-rate regime for exports, and improvements in tax administration.
- Value-added tax. VAT revenues grew significantly slower than GDP in 2023. The primary reason was the reduction of the VAT rate from 15% to 12%. While VAT revenue growth has since accelerated, it continues to trail GDP growth to some extent. At first glance, this trend might be interpreted as evidence of informal economic activity where goods and services are produced but not taxed. However, the main explanation is different. Uzbekistan imposes a zero VAT rate on a significant share of its exports. As exports grow faster than the rest of the economy, VAT revenue growth will naturally lag behind overall GDP growth.
- Personal income tax. The growth of personal income tax revenues has closely tracked nominal GDP growth, suggesting that wage growth and employment expansion have broadly kept pace with economic development.
- Turnover tax. Revenue from the turnover tax has remained largely unchanged over the past four years. This can be explained by the relatively low revenue threshold for applying the regime. Businesses outgrow the turnover tax system quite rapidly and transition to the standard corporate income tax and VAT regime. As a result, turnover tax revenues have limited room for expansion. In this regard, the recent initiative to increase the applicability threshold by nearly five times is a welcome development.
- Other taxes. Other categories of taxation do not have a direct relationship with company revenues or profitability, or they apply only to specific sectors of the economy. Consequently, comparing them to nominal GDP provides less meaningful insights. Economic expansion and increasing export capacity have primarily driven the growth of Uzbekistan’s major tax revenues. A reduction in the shadow economy and improvements in tax administration have also contributed. Legislative reforms, meanwhile, have generally eased rather than increased the tax burden, with the VAT rate reduction being the most significant example.
Adopting best international practices
Uzbekistan's current Tax Code came into force in 2020. During its development, international experience, particularly Russian tax legislation, had a notable influence. At the time of adoption, the code represented a relatively advanced legislative framework, incorporating many modern concepts and tax administration tools.
One notable example is the growing application of the beneficial ownership concept in the taxation of cross-border payments. Recently, tax authorities have increasingly engaged with foreign counterparts and obtained information through international exchange mechanisms.
Today, making cross-border payments such as dividends, interest, or royalties to jurisdictions including the UAE, Singapore, or the Netherlands requires not only tax residency certificates but also compelling evidence that the recipient is entitled to use and enjoy the income received.
Nevertheless, many sophisticated mechanisms embedded in the Tax Code have yet to be widely implemented in practice.
Transfer pricing
The Tax Code contains a comprehensive framework for reviewing whether related-party transactions comply with the arm’s-length principle. Detailed provisions govern the scope of transactions subject to review, acceptable information sources, and approved pricing methodologies.
However, there has been little public evidence of systematic transfer pricing audits conducted under these provisions. Instead, tax authorities tend to rely on Article 248 of the Tax Code, subordinate regulations, and their assessments of market pricing. This approach can reduce certainty and predictability for taxpayers.
Horizontal monitoring
Horizontal monitoring is an advanced compliance model that replaces traditional tax audits with real-time interaction between tax authorities and taxpayers. Under this approach, tax inspectors have continuous access to accounting records and supporting documentation, enabling them to identify issues and discuss corrective actions as they arise.
Countries such as the Netherlands, Austria, the United Kingdom, Kazakhstan, and Russia have successfully adopted this model. In Russia alone, more than 800 of the country’s largest companies participate in the system. Uzbek legislation provides for horizontal monitoring, but it has yet to gain practical traction, and no publicly known cases have been reported.
Controlled foreign companies and tax residency rules
Foreign holding structures are commonly used to attract international investment and facilitate cross-border transactions involving Uzbekistan. At the same time, such structures can also be used to accumulate profits offshore through dividends or service payments.
The Controlled Foreign Company (CFC) rules and provisions allowing foreign companies to be recognised as Uzbek tax residents are intended to address these risks. Nevertheless, since their introduction in 2022, there have been no publicly disclosed enforcement cases.
Consolidated taxpayer groups
Tax consolidation allows companies within the same corporate group to combine their corporate income tax bases. The concept is widely used in jurisdictions such as Germany, France, Austria, and the Netherlands because it simplifies tax administration. Rather than auditing multiple companies separately, tax authorities interact with a designated group representative responsible for compliance. To date, no consolidated taxpayer group has been established in Uzbekistan.
Special rent tax
A special rent tax was introduced into the Tax Code in 2022. However, over the subsequent four years it has not appeared as a separate revenue category in publicly available tax statistics. Possible explanations include the limited number of newly commissioned mineral deposits in 2022-2023, tax relief measures available in 2024-2025, or substantial development costs that delayed profitability. At this stage, the effectiveness of the tax remains difficult to assess.
Overall, the current Tax Code provides a broad range of modern tools available to both tax authorities and taxpayers. While some of these mechanisms are already being actively applied in practice, the full potential of others, including transfer pricing rules, controlled foreign company (CFC) regulations, the special rent tax, horizontal tax monitoring, and consolidated taxpayer groups, has yet to be realised. As Uzbekistan’s tax system and enforcement practice continue to evolve, the importance of these instruments is likely to increase.
At the same time, the capabilities of the current Tax Code represent only one element of the country's broader tax policy agenda. Equally important is the need to respond to global developments in taxation, including international initiatives aimed at introducing a global minimum tax under the OECD’s Pillar Two framework.
Tax incentives and the global minimum tax
The discussion naturally leads to the global minimum tax initiative, known as Pillar Two. In simple terms, Pillar Two reflects an international agreement that multinational enterprises should pay at least 15% corporate income tax, regardless of where they operate. If profits are taxed below that threshold in one jurisdiction, other jurisdictions may impose a top-up tax to bring the effective rate to 15%. Although these rules primarily affect large multinational groups, they illustrate a broader global trend away from corporate income tax exemptions.
Uzbekistan’s tax policy has partly followed this direction, influenced by WTO commitments and OECD recommendations. The zero corporate income tax rate for export activities has been abolished, and profit tax exemptions previously available to free economic zone residents have been replaced with accelerated depreciation mechanisms. At the same time, sector-wide tax incentives remain widespread.
The effectiveness of such incentives is often debatable. In practice, tax exemptions rarely transform an economically unviable project into a profitable one. More often, they benefit businesses that would have invested regardless of tax preferences. As a result, tax incentives may reduce government revenues while distorting capital allocation by encouraging investment toward tax-favoured sectors rather than the most productive opportunities.
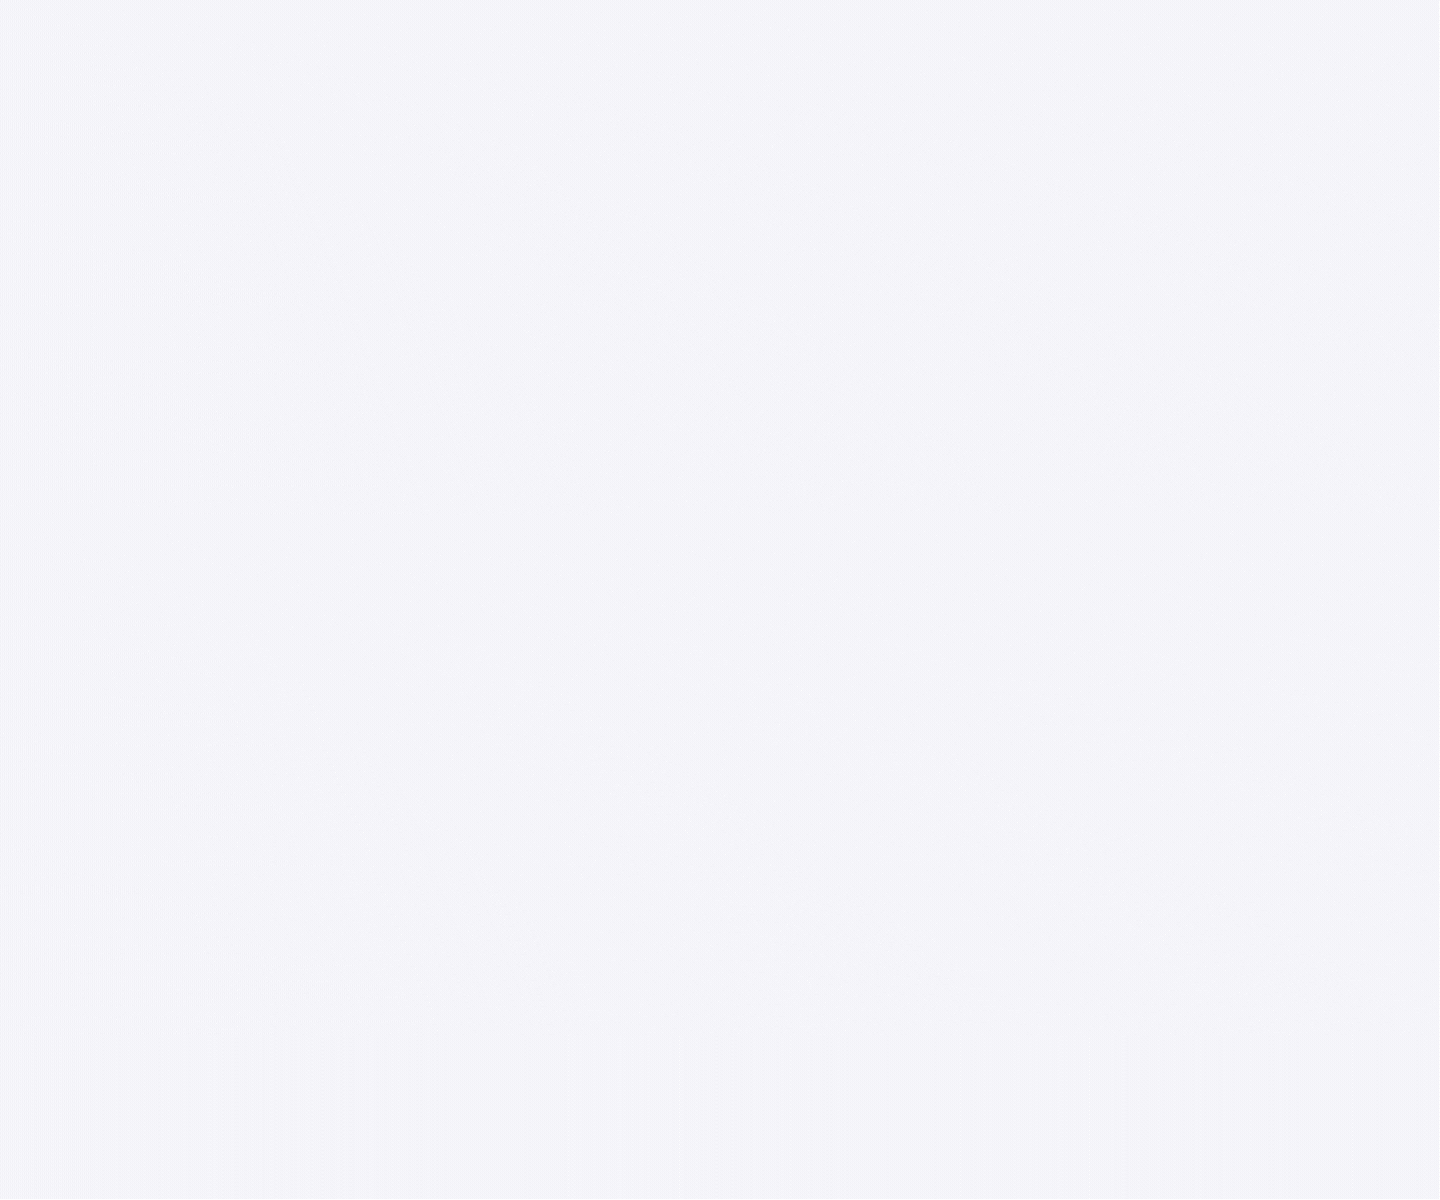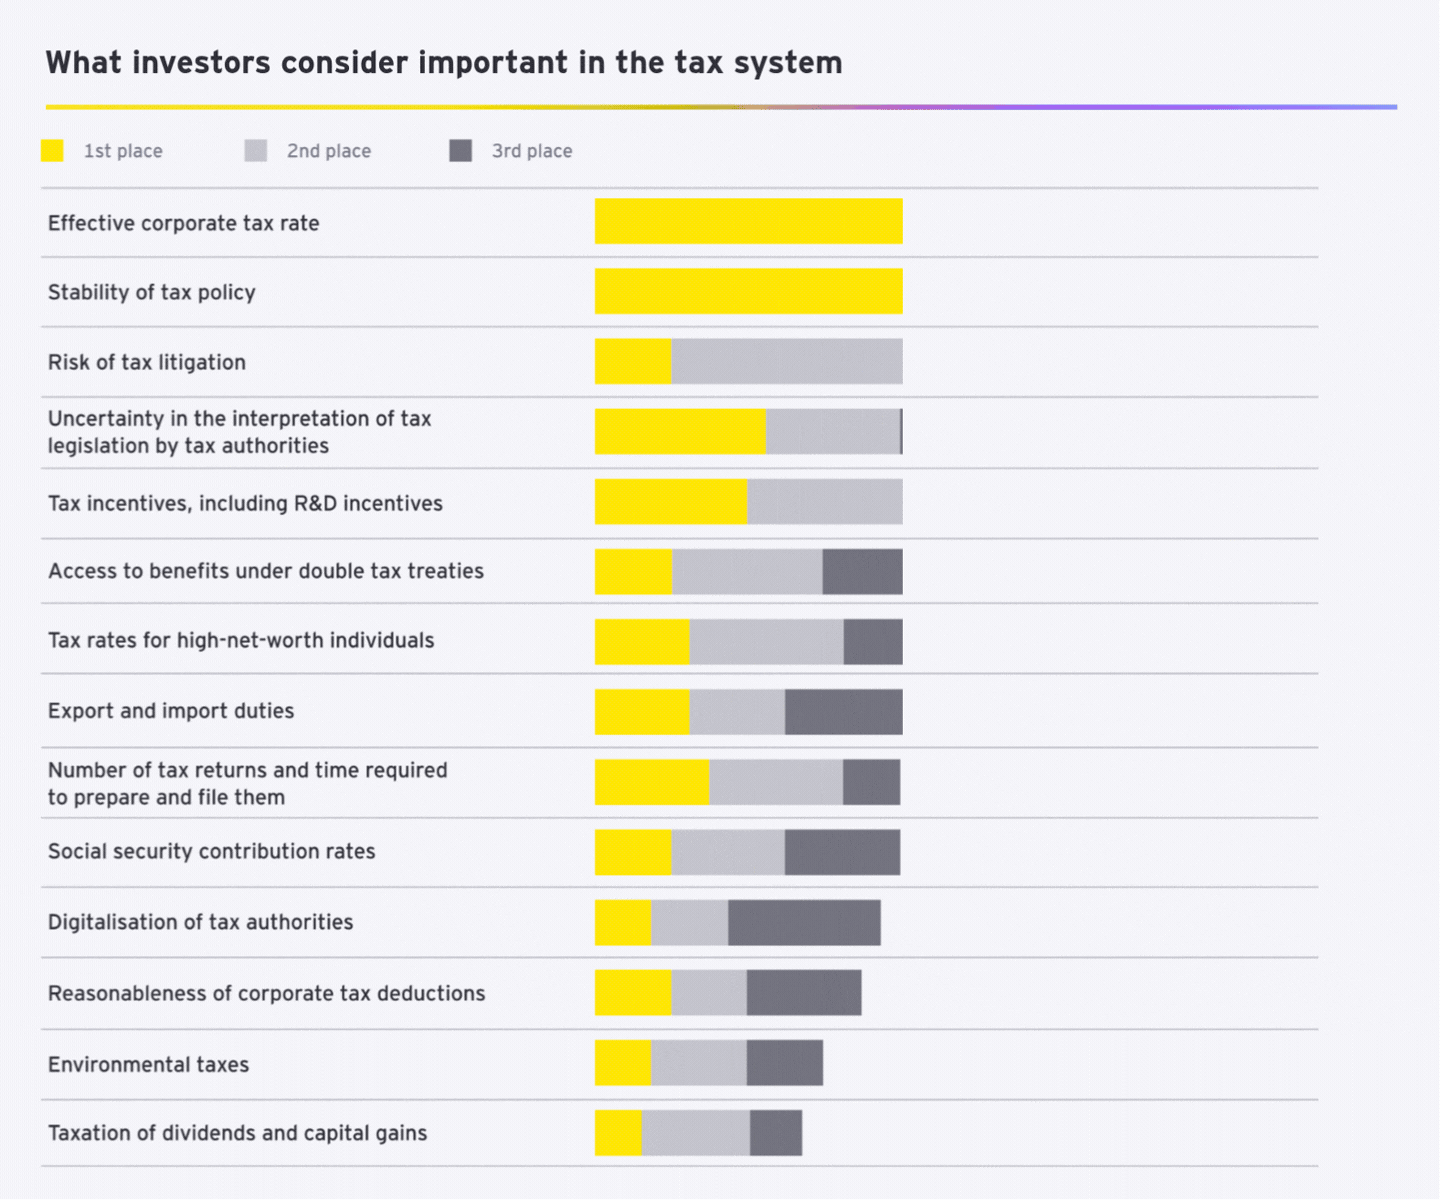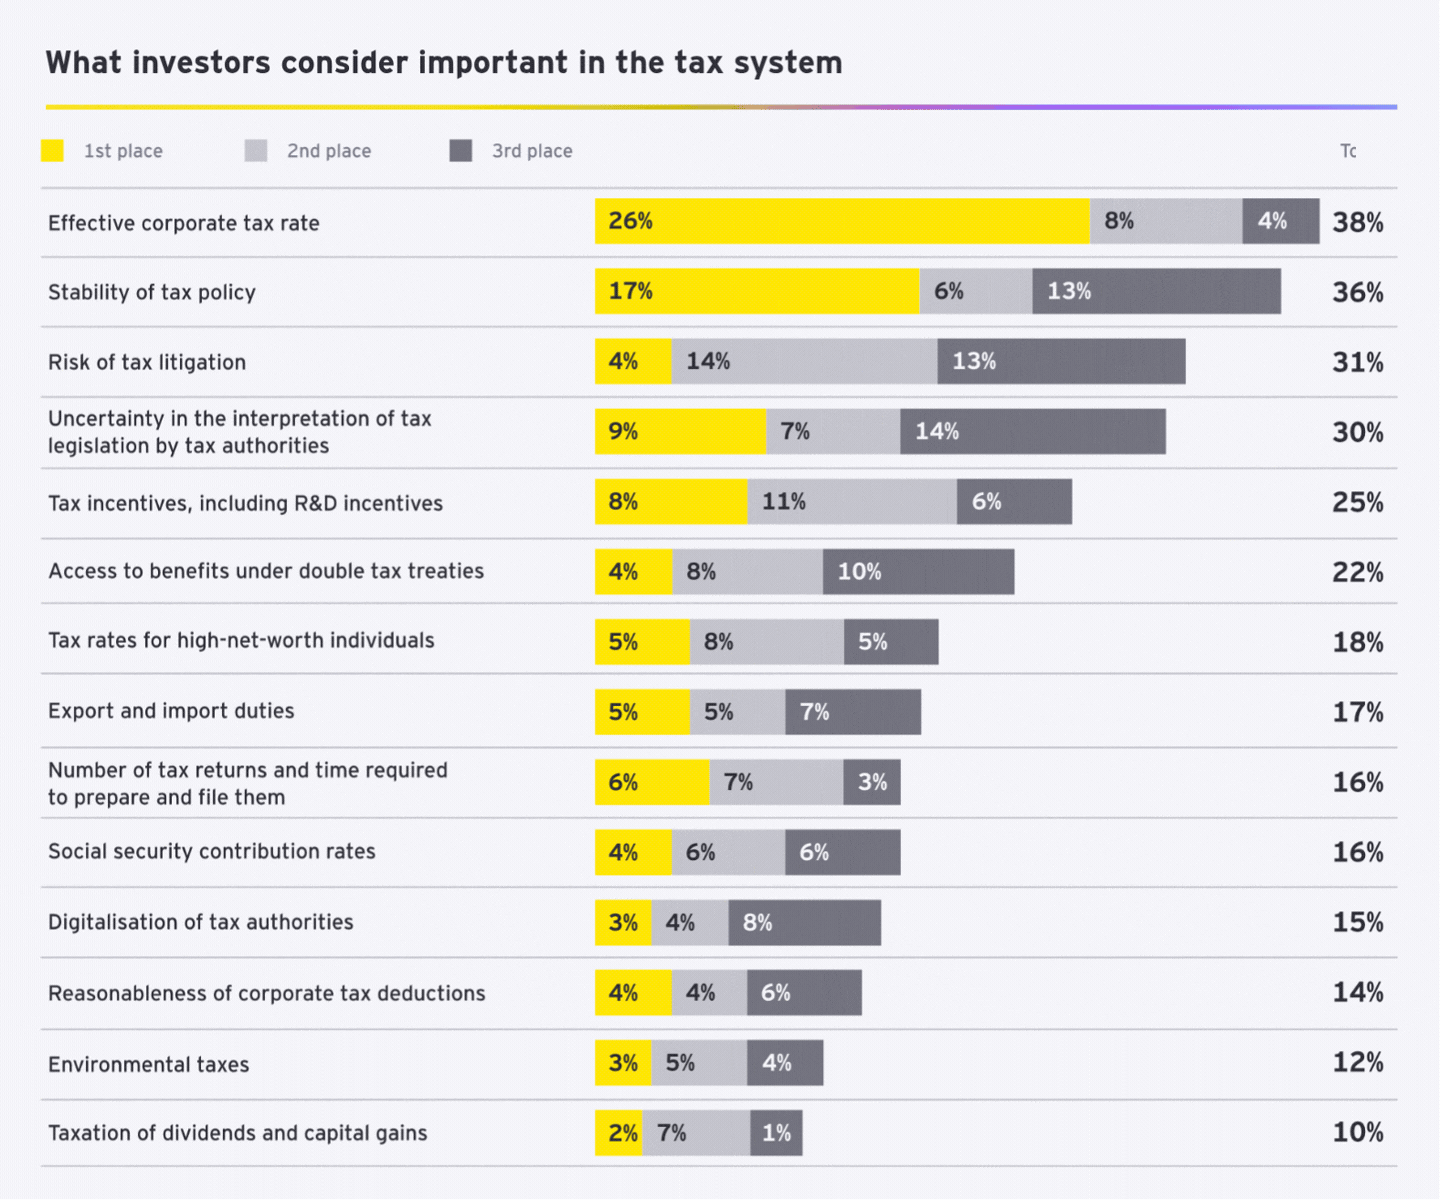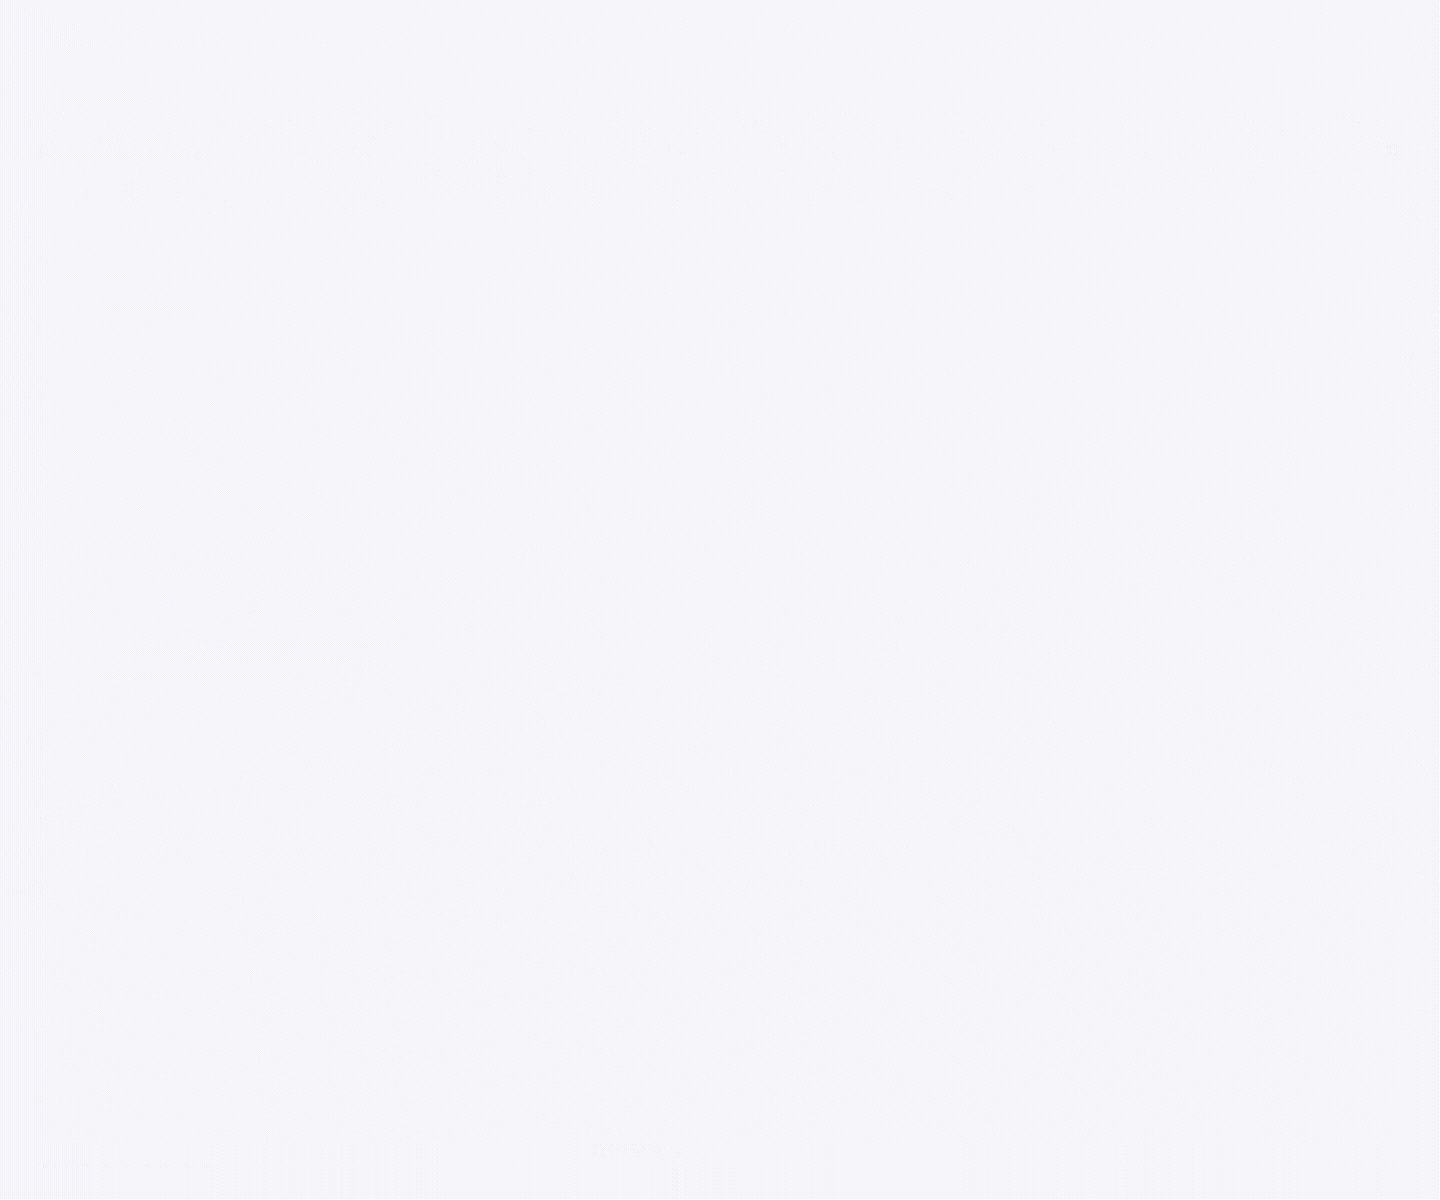
It is also important to remember that Uzbekistan’s attractiveness to investors extends well beyond tax policy. Strong economic growth, a growing and well-educated population, abundant natural resources, constructive international relations, financial stability, and political predictability remain the country’s core advantages. According to EY’s recent Uzbekistan Attractiveness Survey, investors do not consider tax incentives among the most important drivers of investment decisions. Tax incentives ranked only fifth, behind factors such as effective tax rates, predictability of tax policy, tax dispute risks, and consistency in the interpretation of tax legislation.
Even under the standard tax regime, Uzbekistan’s tax burden remains highly competitive compared with neighbouring countries offering similar business conditions.
What matters most to investors, however, is not only the level of taxation but also the clarity of tax rules and the predictability of their application in practice. Even a relatively low tax burden may not offset uncertainty if actual tax liabilities differ significantly from those assumed in an investor’s financial model. This makes the quality of tax administration a critically important factor in the overall investment environment.
Tax administration
No tax code can provide definitive guidance for every situation businesses may encounter. This is entirely normal. In most developed tax systems, such gaps are addressed through administrative practice, such as guidance issued by tax authorities and government agencies, and judicial practice, including publicly available court decisions on tax disputes.
Both sources of interpretation are extremely valuable for businesses because they provide insight into how tax rules are likely to be applied in practice. By observing how similar issues have been resolved in other cases, taxpayers can better understand how to navigate areas where the legislation is unclear. Put simply, a transparent body of tax practice allows the same mistake to be made only once. Future taxpayers can rely on previously established interpretations rather than repeating the same errors.
In Uzbekistan, taxpayers can currently seek clarification from the tax authorities. However, these responses are generally issued on an individual basis, with a specific tax inspector responding to a specific taxpayer. To further strengthen tax administration, Uzbekistan would benefit from establishing public databases of tax rulings and official interpretations. This would promote greater consistency in the treatment of similar issues and significantly reduce compliance errors. Likewise, court decisions on tax matters should be systematically compiled and published on a regular basis, creating a valuable source of guidance for businesses and tax professionals.
Conclusion
Against the backdrop of favourable economic conditions, Uzbekistan has been able to maintain a relatively business-friendly tax policy while continuing to benefit from growing tax revenues driven by overall economic expansion. However, economic growth alone cannot be relied upon indefinitely. Policymakers should already be focusing on how to ensure the long-term sustainability of the tax base without resorting to higher tax rates.
This can be achieved through broader use of the tools already available under the Tax Code, alignment with global tax developments, a more selective approach to tax incentives, and greater predictability for taxpayers through continued improvements in tax administration. Together, these measures can help strengthen both fiscal stability and Uzbekistan’s attractiveness as a destination for long-term investment.